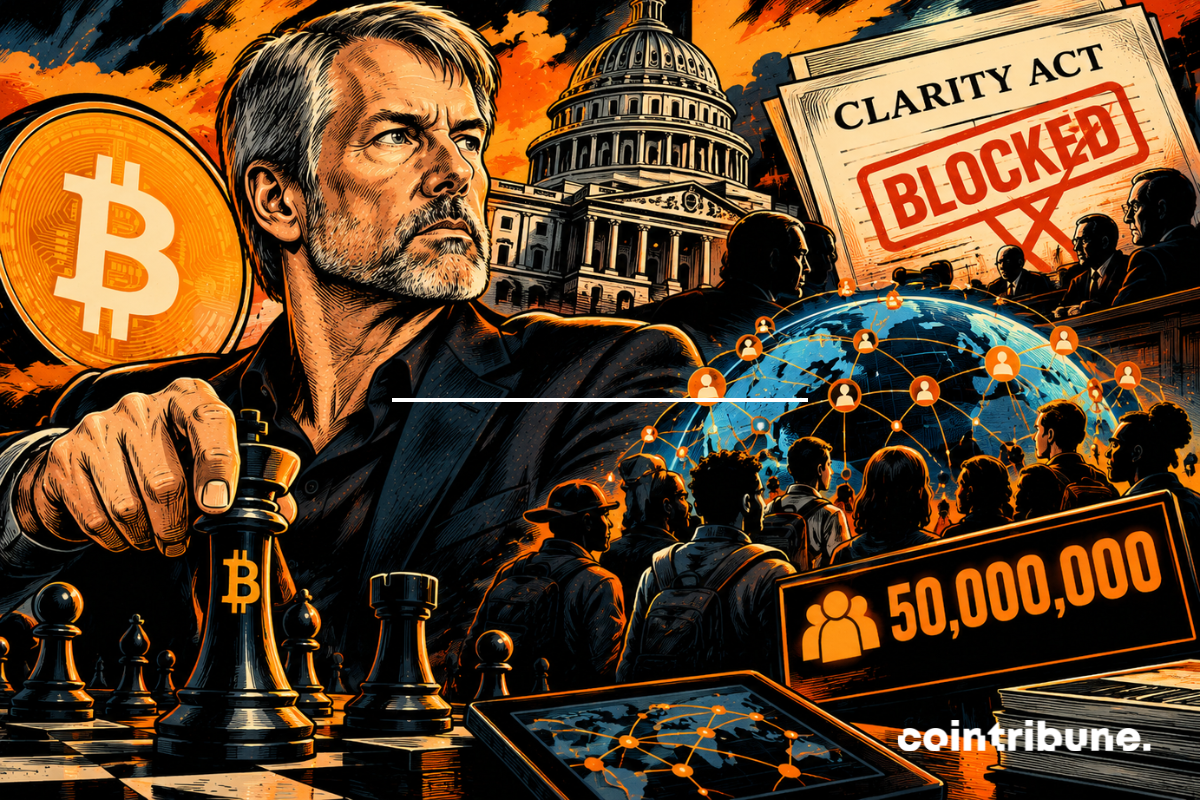
The CLARITY Act was intended to provide digital assets with a more readable federal framework in the United States. But on September 15, the Senate failed to move the text forward: the closing motion failed by 49 votes to 50. No final vote on the law, therefore, but a serious brake. In the process, Saylor changes terrain. Rather than waiting for another attempt in Congress, he wants to use the next two years to accelerate the adoption of digital financial products.
In brief
- The US Senate blocks progress on the CLARITY Act after a procedural vote concluded with a score of 49-50.
- Saylor is changing his approach and wants to accelerate the adoption of digital financial products rather than waiting for a new law.
- Bitcoin, credit, tokenized shares and stablecoins make up the main building blocks of the strategy defended by Saylor.
- The SEC and CFTC continue to act despite the blockage, particularly around tokenization and digital markets.
- In the United States, the absence of the CLARITY Act mainly creates a fragmented framework, rather than a real regulatory void.
The CLARITY Act stalls in the Senate, Saylor is already looking elsewhere
The details of the vote are important. The Senate has not definitively rejected the CLARITY Act on its merits. This is the procedure to pave the way for its examination which did not obtain the necessary 60 votes. The text therefore remains blocked, while the sector expected from this law more precise rules on digital assets and the sharing of skills between regulators.
Saylor does not suggest sitting idly by. In his text published on September 19, he defends a different approach: use the possibilities offered by the SEC, the CFTC, the Treasury and the banking authorities, then put more products in the hands of the public.
His argument rests on adoption. The more users there are, the more difficult it becomes to go back. It is therefore targeting 50 million satisfied users.
Our safest path is to create products that appeal to customers and deploy them widely. Lower costs, easier access, useful services and greater control over money give users a vested interest in preserving innovation.
Michael Saylor – X
Bitcoin, credit, stocks: Saylor’s strategy involves products
Behind this idea of adoption, there is a fairly precise architecture. Bitcoin constitutes “digital capital”. STRC must provide a credit dimension. MSTR stands for stocks. Coinbase intervenes on the platform side and USDC on the payments side. Saylor presents these building blocks as elements of the same financial system.
The objective is therefore not only to make people buy more crypto. This involves offering services that more closely resemble those of traditional finance: holding an asset, borrowing, investing, transferring money or trading securities.
The movement is already visible on the side of the regulators. On September 17, the SEC granted a temporary and conditional exemption to certain platforms to allow trading in tokenized US stocks. The measure is set to expire after five years. It also imposes several conditions, in particular on the rights attached to the securities and the protection of investors.
Paul Atkins presents this decision as an experimental step before possible more lasting rules:
The innovation exemption, although temporary, would allow platforms to trade tokenized NMS shares today in a permitted environment, while the Commission studies the need for further measures.
Paul Atkins – SEC
After the vote, the crypto industry must deal with several paths
Blocking the CLARITY Act does not mean regulatory activity stops. It’s even the opposite. The SEC is moving forward on tokenized stocks, while the CFTC continues its own work. For businesses, the landscape is therefore becoming more fragmented.
This situation also provokes different reactions. Arthur Hayes downplayed the bill and placed the sequence in the broader context of US monetary policy. Other observers believe that a federal law would have provided a more stable basis for businesses than exemptions or decisions taken by agencies.
The two approaches do not produce exactly the same result. An administrative measure can allow an activity to start quickly. A law passed by Congress can establish more lasting rules and formally modify the powers of the authorities.
For the crypto sector, the immediate problem is therefore less the total absence of rules than the uncertainty about their next step. Companies must move forward in an environment where several institutions can act separately.
Saylor’s bet is precisely to take advantage of this period rather than endure it.
In the United States, the “regulatory void” mostly resembles an open construction site
To speak of an American regulatory void would be excessive. Digital assets remain subject to existing rules, and regulators continue to intervene. The SEC has just demonstrated this again with its exemption dedicated to tokenized shares.
What is especially missing is the broad common framework that the CLARITY Act was supposed to help establish. Without it, companies must contend with initiatives from multiple agencies, with measures that may vary in duration and scope.
This is also where the limit of the strategy defended by Saylor lies. Having a product adopted by millions of people can create economic and political demand around this service. But adoption does not resolve jurisdictional issues between the SEC and the CFTC. It also does not replace a law when Congress is necessary to modify the federal framework.
The next step could therefore be played out on two fronts. Companies continue to develop their products while agencies test the limits of their powers. At the same time, a new legislative attempt remains possible.
To remember:
- 49-50: result of the procedural vote in the Senate on September 15;
- 5 years: expected duration of the SEC temporary exemption;
- 50 million: user objective put forward by Saylor.
The regulatory debate is evolving, but Bitcoin remains Saylor’s fixed point. Jason Calacanis believes that the asset has not yet found its wide popular use. Saylor answers differently: approximately $1.6 trillion in capitalization and 845,050 BTC held by Strategy at the end of August. For him, BTC therefore does not need to become the universal means of payment imagined in its infancy. It can be defended as a form of digital capital. Skepticism remains present, but its position does not change: “ The orange tie stays. »
Maximize your Tremplin.io experience with our ‘Read to Earn’ program! For every article you read, earn points and access exclusive rewards. Sign up now and start earning benefits.