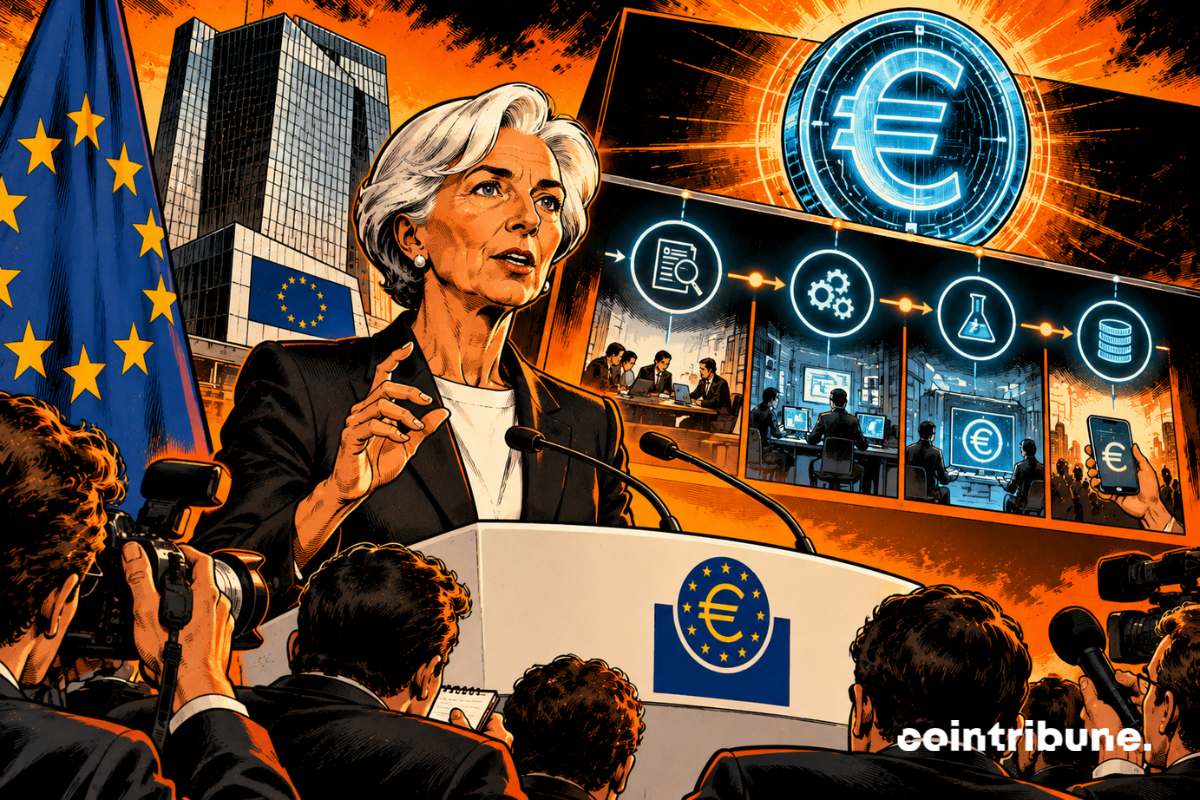
Christine Lagarde believes that the euro zone economy is resilient to global shocks and confirms the progress of the digital euro project. However, its arrival is not imminent for the public: the ECB is planning an internal pilot in the second half of 2027 and could only carry out a first issue in 2029, subject to the prior adoption of the European regulation.
In brief
- The ECB plans the first tests for the digital euro in the second half of 2027, before a possible issuance in 2029.
- The launch depends on the adoption of the European regulation and the final validation of the ECB.
- The digital euro aims to reduce Europe’s dependence on foreign payment solutions.
- Christine Lagarde highlights the resilience of the euro zone despite trade, energy and geopolitical tensions.
- The ECB anticipates gradual growth, but remains vigilant in the face of inflation and cybersecurity risks.
A digital euro pilot planned for the second half of 2027
The President of the European Central Bank presented the next steps of the project on October 17 at the annual meetings of the International Monetary Fund. The immediate priority is the adoption of the European legal framework before the end of 2026.
THE official calendar remains subject to several conditions:
- The European Parliament and the Council must adopt the digital euro regulation;
- The ECB will only decide on an issue after the adoption of this legislation;
- A twelve-month internal pilot is due to begin in the second half of 2027;
- The version tested will not be legal tender and will not constitute a true digital euro;
- A first emission could take place in 2029 if the previous stages are successful.
The ECB has already launched a call for applications from online and mobile merchants in the euro zone. Selected participants will test a beta version in a controlled environment, with national central banks and payment service providers.
The project must reproduce concrete situations, such as a payment in store, an online purchase or a transfer between individuals. The trials will focus on security, ease of use, integration with merchant systems and the ability of the infrastructure to operate at scale.
Christine Lagarde has explain :
To prepare for a smooth and secure launch, we will conduct a twelve-month internal pilot in the second half of 2027.
She added that adopting the regulation before the end of 2026 was essential to meet this timetable.
The ECB wants to reduce dependence on foreign players
The digital euro would be an electronic form of central bank money intended for everyday payments. It would complement the notes and coins without replacing them. Individuals and businesses could use it across the euro area through banks or other authorized providers.
For the ECB, the project responds to a sovereignty issue. A large part of European electronic payments currently relies on international bank card groups, foreign technology platforms or private solutions whose access depends on commercial decisions.
The digital euro must provide a common public infrastructure while maintaining coexistence with private means of payment. Christine Lagarde believes it will promote innovation and competition in retail payments and strengthen Europe’s strategic autonomy.
The ECB also promises a higher level of confidentiality than traditional commercial solutions. She says she would not seek to identify individual purchases. For offline payments, the data would only be known to the payer and the payee, according to the architecture currently envisaged.
The project should not be confused with Pontes, the solution using distributed ledger technology launched by the Eurosystem on September 21. Pontes concerns the settlement of tokenized assets between financial institutions. The digital euro targets, for its part, current payments by individuals and merchants.
A resilient economy, but still exposed to risks
Christine Lagarde at the same time described a euro zone economy that was more solid than expected despite trade tensions, the conflict in the Middle East and the energy shock. Growth was spread across several countries and sectors in the first half of 2026.
The ECB’s September projections anticipate growth of 0.9% in 2026, then 1.4% in 2027 and 1.5% in 2028. The recovery in real incomes, the resilience of the labor market and spending on infrastructure, defense and artificial intelligence should support activity.
The risks nevertheless remain oriented to the downside for growth and the upside for inflation. A prolongation of the conflict in the Middle East could keep energy prices high. Trade tensions and protectionist policies are also weighing on investments.
The ECB judges euro zone banks sufficiently capitalized and liquid to face these uncertainties. However, she is concerned about the risks linked to critical technology providers, the concentration of digital services and new cyber threats fueled by artificial intelligence.
The digital euro is therefore part of a broader financial strategy. It must modernize European payments, but its launch still depends on a political decision, a conclusive pilot and a final vote by the Governing Council of the ECB.
Maximize your Tremplin.io experience with our ‘Read to Earn’ program! For every article you read, earn points and access exclusive rewards. Sign up now and start earning benefits.